TL;DR

Turn quiet afternoons into listening time
- Thousands of audiobooks, podcasts and originals
- Listen on your phone, tablet or Echo — also offline
- Cancel anytime
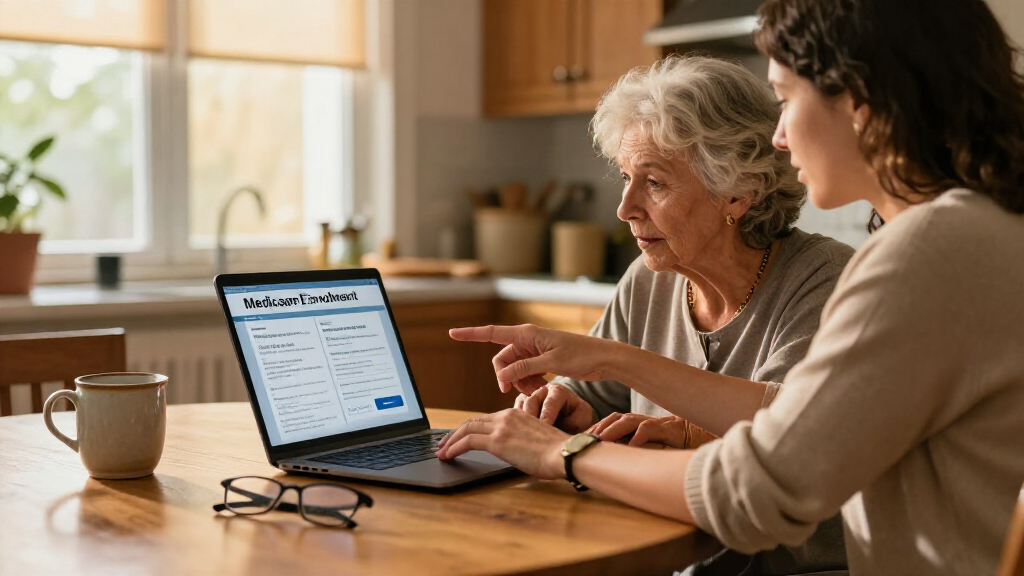
Seniors Guide has republished a Kiplinger’s Personal Finance report outlining six additional Medicare mistakes, with a focus on enrollment deadlines, coverage coordination and income-related premium surcharges. The supplied article gives details for five mistakes but cuts off partway through the fifth, so the sixth mistake and the full guidance on appealing a surcharge are not available in the source material.
Seniors Guide has published the second part of a Kiplinger’s Personal Finance report on Medicare mistakes, describing risks tied to enrollment deadlines, retiree and COBRA coverage, and income-related premium surcharges. The supplied text details five of the six listed mistakes and ends before completing the fifth, leaving the sixth item and some appeal guidance unavailable.
The report says people who are not already receiving Social Security benefits generally need to take action to enroll in Medicare when they become eligible at 65. It describes a seven-month initial enrollment window that starts three months before the month of a person’s 65th birthday and ends three months afterward. Some people may be able to delay Part B if they or a spouse has coverage through a current employer; the article cautions that employer size can affect which coverage pays first.
It distinguishes coverage through a current employer from retiree coverage and COBRA. According to the report, those arrangements generally do not count as current-employer coverage that allows someone to delay Part B without potential consequences. It also says people leaving qualifying employer coverage may have an eight-month special enrollment period to sign up for Part B, and that missing applicable deadlines can mean a coverage gap or a late-enrollment penalty.
The report also warns that income can affect Part B and Part D costs. It gives the 2026 standard Part B premium as $202.90 per month and says income-related surcharges may apply based on tax information from two years earlier. Its stated 2026 thresholds are 2024 adjusted gross income above $109,000 for single filers or $218,000 for joint filers. These are figures reported in the source and may not apply to other years or individual circumstances.
Deadlines Can Affect Coverage and Costs
The mistakes described in the report can affect both access to coverage and household budgets. Late enrollment may leave a person without expected coverage for a period, while the report says some Part B late-enrollment penalties can raise premiums for as long as the person has Part B. The impact depends on a person’s enrollment history and whether they qualify for an exception or special enrollment period.
Income-related adjustments can also raise monthly costs for Medicare beneficiaries whose income exceeds the relevant thresholds. The report flags Roth conversions and large withdrawals from tax-deferred accounts as financial moves that can increase adjusted gross income. That is a planning issue, not a recommendation to avoid any particular transaction: the source does not assess an individual’s tax situation, and Medicare premiums are only one consideration in retirement decisions.
The practical takeaway is that people approaching 65, leaving work, or changing employer coverage should confirm their own enrollment dates and how their insurance coordinates with Medicare. Coverage labels alone may not determine whether someone can delay enrollment; the details of the employer plan and the person’s circumstances matter.
Popular right now

Samsung 85-Inch QN70H Neo QLED 4K Smart TV (2026)

Ninja Foodi 10-Qt DualZone Smart XL Air Fryer, 6-in-1, DZ550

Vitamix Propel Series 750 Professional-Grade Blender, 4 Programs, Black
As an affiliate, we earn on qualifying purchases.
How Enrollment Windows Work
The report is presented as Part II of a two-part series. It says the first installment covered five other common Medicare mistakes; the supplied material focuses on six additional ones. Medicare enrollment and coordination rules can vary depending on whether a person is working, has coverage through a current employer, and whether that employer meets the relevant size threshold.
For people who qualify to delay Part B because of current-employer coverage, the report describes an eight-month period to enroll after work or the group health plan ends. It says enrollment may also be possible while a spouse continues working, depending on when employment or the group plan ends. The article advises readers to ask the employer whether Part B can be delayed and points to Social Security Administration information for people applying for Medicare only.
The source also discusses health savings accounts. It says people enrolled in Medicare cannot contribute to an HSA and warns of a six-month lookback rule when someone later enrolls in Medicare. The details of that rule and its application depend on a person’s circumstances, so the report’s brief warning is not a substitute for checking current official guidance.
“You have a seven-month window to sign up — from three months before your 65th birthday month to three months afterward.”
— Seniors Guide, summarizing the report’s enrollment guidance
Missing Details in the Supplied Report
The source text ends partway through the section on contesting an income-related surcharge after retirement. It does not provide the rest of that guidance or identify the sixth Medicare mistake, despite describing the article as a six-item list. The available material also does not give a publication date, so the figures and rules should be checked against current Social Security Administration and Medicare information before readers act on them.
The source provides broad descriptions rather than individual eligibility decisions. Whether a person can delay Part B, qualifies for a special enrollment period, faces a penalty, or can appeal an income-related adjustment depends on details not included here. The article also does not establish that any particular financial transaction will result in a surcharge for every reader.
Check Dates and Current Rules
Readers approaching 65 or leaving a job should confirm their enrollment window and coverage status with the Social Security Administration, Medicare, and their employer’s benefits administrator. Those considering delaying Part B should verify that their coverage is through a current employer and ask how employer size affects primary coverage. People with HSA contributions should check timing rules before enrolling in Medicare.
Anyone facing an income-related surcharge after a retirement or another life change can ask Social Security about the agency’s appeal process and what documentation may be required. The supplied report indicates that an appeal may be relevant when income has fallen after certain life-changing events, but it cuts off before giving the full criteria. Readers should rely on current official instructions or qualified tax and benefits professionals for decisions based on their specific circumstances.
Key Questions
What is the news in this report?
Seniors Guide published part two of a Kiplinger’s Personal Finance report listing additional Medicare mistakes. The supplied text covers enrollment timing, coverage coordination and income-related premium surcharges, but does not include the complete six-item list.
When does the initial Medicare enrollment window begin and end?
The report describes a seven-month window: it begins three months before the month of a person’s 65th birthday and ends three months afterward. Readers should confirm their own dates with Social Security or Medicare.
Does retiree or COBRA coverage let someone delay Part B?
According to the report, retiree coverage and COBRA generally do not count as coverage through a current employer for this purpose. Individual circumstances can vary, so people should verify their status before delaying enrollment.
What income figures does the report give for 2026 surcharges?
The report says 2026 income-related adjustments may apply when 2024 adjusted gross income exceeded $109,000 for single filers or $218,000 for joint filers. These are source-reported figures; readers should check current official thresholds for the relevant year.
What is missing from the source material?
The supplied text stops during its discussion of appealing a surcharge after retirement. It does not include the full appeal guidance or the sixth mistake named in the report’s introduction.
Source: rss